causation reports
Updated November 6, 2026
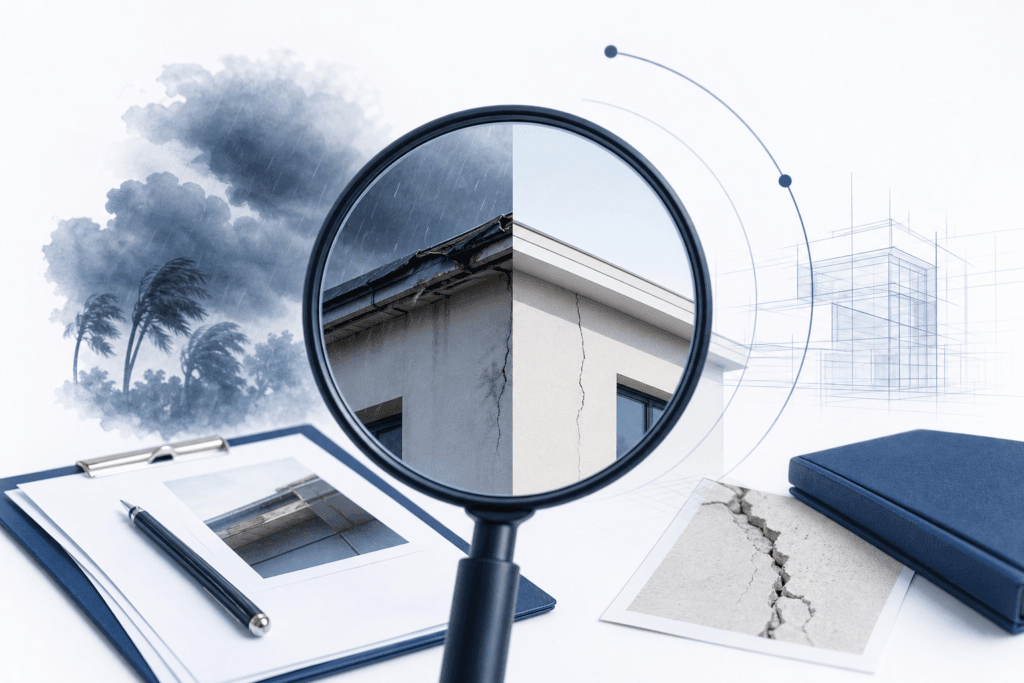
A causation report is an independent expert document that links a specific cause to a specific effect, such as showing that storm damage, not poor maintenance, caused a leak. It sets out inspection findings, photographs, standards references and a reasoned conclusion, and is used to challenge an insurance denial or support a dispute.
A lot of people arrive at this the same way. They don't start by searching for causation reports. They start with a stained ceiling, a swollen skirting board or a cracked wall, and then a letter from their insurer that says the claim has been declined. The claim is denied, the repairs are still needed, and nobody has explained how the insurer reached that conclusion.
This guide explains what a causation report is, why it matters when a claim or dispute turns on "what caused this?", and what a good one contains. It also covers who should prepare it and how the process runs. The worked context is NSW building disputes, and the reasoning applies to property damage matters more broadly. If you want to see how this kind of document looks in practice, you can also read 7 expert witness report examples for NSW disputes, and the page's author details are on the author profile.
What is a causation report?
A causation report is a document in which a qualified, independent expert explains what caused a particular loss or damage, and shows the evidence behind that conclusion. It connects two things: the cause (an event, a defect or a failure) and the effect (the damage you can see). The report exists because damage rarely announces its own origin.
Take a water stain on a bedroom ceiling. It might come from a failed roof flashing, a burst pipe, a storm event, a failed bathroom membrane in the room above, or years of slow condensation. Each cause points to a different party and a different outcome. If a storm caused it, an insurer may be liable. If a builder installed the flashing incorrectly, the builder may be. If the roof was never maintained, the owner may carry the cost. The repair might look identical in every case. The responsibility does not.
A causation report resolves that question by working backwards from the damage, and it is easy to share with your solicitor, insurer or builder once it is finished. The expert inspects the site, records what is there, tests what can be tested, and reasons from the evidence to the most probable cause. The conclusion is only as strong as the observations underneath it, which is why the report records its method, its photographs and its limits as well as its opinion.
In practice, causation reports are used in a few main settings:
- Insurance claims: to respond to a denial, or to support a claim before one is made, by showing the damage came from an insured event rather than gradual deterioration.
- Building disputes: to establish whether a defect resulted from workmanship, materials, design or an external event, including in NCAT proceedings.
- Court and tribunal matters: to give a decision-maker independent expert evidence on what produced the loss.
- Negotiations between parties: to move a disagreement from competing opinions to documented findings.
This is not the same as a general defect report. A defect report records what is wrong. A causation report explains why it happened, and that "why" is usually what decides who pays.
Breach of duty versus causation: why proving one is not enough
Breach of duty and causation are two separate questions, and a claim usually needs an answer to both. Breach of duty asks whether someone fell short of the standard expected of them. Causation asks whether that shortfall actually produced the loss. Proving the first does not prove the second.
A building example makes the difference clear. Suppose a builder installed a bathroom waterproofing membrane without the required upturn at the wall junction. That is a breach: the work does not meet the relevant Australian Standard for waterproofing of domestic wet areas. Now suppose the owner later finds water damage in the hallway outside the bathroom. The breach is established on paper, but the owner still has to show that the missing upturn is what let the water out. If the damage came instead from a leaking pipe behind the wall, the defective membrane did not cause this loss, however non-compliant it is.
The reverse also happens. An owner can have clear damage and a plausible suspect, yet no evidence tying the two together. The tribunal or insurer is left with a defect on one side and a loss on the other, and nothing connecting them.
This is where a causation report earns its place. A defect inspection can establish the breach. The causation analysis addresses the link, by tracing moisture paths, ruling out alternative sources and explaining why the identified failure accounts for the damage found. Where there are several possible causes, the report says which were considered and why some were set aside.
The same split appears well outside building. In medical negligence, a clinician may have fallen below the expected standard of care, but the patient must still show that the lapse caused the harm. Research by the Doctors Company covering 735 radiology claims between 2010 and 2025 found that approximately 75% of malpractice claims were caused by errors related to diagnosis. Even with a pattern that clear, each individual claim still turns on whether the specific error produced the specific injury. The principle is the same in a leaking shower as in a missed diagnosis: a shortfall in standard is only half the case.
For building owners, the practical point is simple. A report that lists defects does not, on its own, answer the question an insurer or tribunal is asking. If your matter turns on what caused the damage, you need evidence that addresses cause directly.
Why was my insurance claim denied for maintenance or wear and tear?
Insurers deny many property claims by classifying the damage as the result of gradual deterioration or lack of maintenance, which most policies exclude, rather than a sudden insured event. A denial on these grounds usually rests on an assessor's view that the damage developed over time. It does not necessarily rest on proof that it did.
Most home policies cover defined events such as storm, fire, escape of water or impact. They typically do not cover wear and tear, rust, rot, or damage that results from an owner failing to maintain the property. The difficulty is that the two categories overlap in practice. A storm can drive water through a roof that was already ageing. A burst pipe can be the final failure of a fitting that had been corroding for years. The insurer's assessor may focus on the ageing and treat the event as incidental.
The scale of this is not small. According to an Insurance Council of Australia (ICA) submission, insurance denials based on maintenance and wear and tear exclusions increased to 51% of all claim denials in 2023. Separately, a General Insurance Code Governance Committee (CGC) inquiry involving a sample of 42,956 denied home insurance claims found that 55% of those denials were based on maintenance or wear and tear exclusions. These are two different sources with different samples and should not be read as a single figure. Taken together, they point the same way: maintenance and wear-and-tear exclusions account for a majority of the denials that were examined.
If you have received a denial like this, the useful question is what evidence the insurer relied on. Often it is a short assessment by the insurer's own representative, based on a limited inspection. It may state a conclusion ("long-term moisture damage") without showing the testing or reasoning behind it.
A causation report responds on the same ground. It does not argue that maintenance never matters. It examines whether the specific damage you have is consistent with the insured event or with gradual deterioration, and it shows the basis for that finding. That might include moisture readings that map a recent water path, the condition of materials around the damage, the timing of the event against weather records, and the presence or absence of the long-term signs an insurer's assessor described.
The report can also separate a pre-existing condition from the damage that followed. A roof with some age is not the same as a roof whose damage was caused by age. Where the evidence supports it, the report states that the event produced the loss even though maintenance issues existed. Where it does not, an honest report says so, which spares you from escalating a claim the evidence will not support.
Who prepares a causation report for property damage?
A causation report should be prepared by an independent expert with the practical building experience to inspect the damage and the standing to give evidence on it. That usually means a building consultant, a licensed builder with forensic experience, or a specialist engineer, depending on what failed. What matters most is that the author has no stake in the outcome.
Independence is the point on which the whole document rests. Three kinds of author are commonly offered to a homeowner, and only one is a safe choice.
- The insurer's assessor: This person is engaged and paid by the party deciding your claim. Their report may be competent, but it is not independent, and a tribunal or reviewer will read it that way.
- The tradesperson who did or repaired the work: A builder or plumber asked "what went wrong?" has a direct interest in the answer. If the cause is workmanship, the person being asked may be the person responsible.
- A professional who treated the problem: A contractor who attended the leak and carried out the repair can describe what they found. That is a factual account, not an independent opinion on cause.
An independent expert owes a duty to the tribunal or decision-maker, not to whoever pays the invoice. In NSW tribunal and court matters, that duty is set out in the Expert Witness Code of Conduct, which requires the expert to give an honest, impartial opinion within their field of expertise. A report written to that standard states its assumptions, discloses what was and was not inspected, and does not advocate for either side.
Awesim Building Consultants is an independent building consultancy that prepares expert witness reports and forensic inspections for homeowners, builders, solicitors and strata managers in NSW disputes, including matters before NCAT and the NSW courts.
Whoever you engage, a few checks are worth making before you commit:
- Relevant field experience: a waterproofing failure calls for different expertise from a structural movement problem.
- Tribunal experience: familiarity with NCAT procedure and the expert evidence requirements saves rework later.
- Independence from the parties: no ongoing commercial relationship with the builder, insurer or opposing side.
- A willingness to say "the evidence does not support that": an expert who only ever agrees with the client is of little use to a tribunal.
If a solicitor is already involved, they will often prefer to instruct the expert directly. That keeps the lines of instruction clean and makes the independence of the report easier to demonstrate.
What a causation report contains: an expert witness report example
A causation report follows a fixed sequence so that a reader can trace every conclusion back to an observation. Each component answers a question the decision-maker is likely to ask. The outline below is the structure a competent report works through.
- Scope and instructions: Who engaged the expert, what questions they were asked to answer, and what documents they were given. This fixes the boundaries of the opinion.
- Qualifications and Code of Conduct declaration: The author's relevant experience and a statement that they have read and complied with the Expert Witness Code of Conduct.
- Inspection method: The date, who attended, weather on the day, access limits, and the instruments used, such as a moisture meter or thermal imaging camera.
- Observations: What was found, recorded neutrally and measured where possible, without drawing conclusions yet.
- Photographic record: Images that establish location, show the defect and give scale. A reliable protocol is an establishing shot, a medium shot and a close-up with a ruler in frame.
- Analysis: The reasoning that moves from observations to a cause, including the alternative causes considered and why they were set aside.
- Standards and code references: The specific clauses of the NCC (formerly the Building Code of Australia) or the Australian Standard against which the work was assessed.
- Limitations: What was not inspected and why, for example a sub-floor space that was not accessible.
- Conclusion: A clear statement of the most probable cause, in terms the reader can act on.
Here is a short worked example of how one finding is built, so you can see the pieces connect.
Observation: Elevated moisture readings at the base of the hallway wall adjoining the bathroom, against much lower readings on the opposite wall of the same hallway. Photograph: Staining and swollen skirting at the same location, with a ruler for scale. Test: A ponding test on the shower base showed water loss at the wall junction. Standard: The membrane did not return up the wall to the height required by the relevant Australian Standard for waterproofing of domestic wet areas. Alternative considered: Plumbing supply lines in the wall were pressure tested and held, which excludes a pipe leak. Conclusion: The water in the hallway wall most probably escaped through the shower junction where the membrane was deficient, not through a plumbing failure or a one-off storm event.
Each line there carries weight. The measurement shows the damage is real and localised. The test links it to a source. The standard shows why the source is a defect. The excluded alternative closes off the other explanation. Remove any one and the conclusion gets easier to attack.
This is also why a generic report fails. A causation report cannot be a template with the address swapped in. The observations, the tests and the excluded alternatives are specific to one property and one set of damage, and a decision-maker will notice boilerplate immediately. A template can supply the structure above. It cannot supply the findings.
Consider what each section protects against. The scope section stops anyone arguing the expert answered the wrong question. The method section lets another expert repeat the inspection and check the result. The limitations section shows the author was candid about what could not be seen, which makes the rest of the report more credible. A reader who finds all three present can usually follow the logic from the first page to the last without needing to ask the author for help.
If you are weighing up what these reports look like in a wider legal setting, the guide on Construction Claims Experts and Witness Reports explains how this kind of report sits alongside other expert evidence in a dispute.
Checklist: how to prepare for a forensic building inspection
The more the expert has in hand before arriving, the less time the inspection spends on gathering background and the more it spends on the damage itself. Collect the following before the visit and keep copies, not originals.
- The denial letter and policy wording: The letter shows the stated reason for the decision. The policy schedule and product disclosure statement show what is covered and which exclusions apply. The expert needs both to know which question the report must answer.
- Dated photographs of the damage: Images taken when you first noticed the problem, and any taken earlier of the same area, show how the damage developed. Phone images carry date data that helps establish a timeline.
- Maintenance and repair records: Invoices, quotes and service records show what upkeep was done. They answer a "lack of maintenance" argument directly, and they equally show honestly where work was overdue.
- Building plans and approvals: Plans, specifications, certificates and any council approvals tell the expert what was meant to be built, which is the baseline for judging what was built.
- Weather dates: Note the date of any storm or heavy rain you connect with the damage. The expert can check it against weather records.
- Access arrangements: Make sure the expert can reach roof spaces, sub-floors, cupboards and the areas around the damage. Limited access becomes a limitation in the report.
- A timeline of symptoms: A short written list of what you noticed and when, such as the first stain, the smell, the swelling and the day the claim was lodged.
- Correspondence and deadlines: Emails and letters with the insurer or builder, and any dates for responding or lodging a review, so the report is ready in time.
Two items on that list are worth a note. Do not repair or remove the damaged material before the inspection unless it is unsafe to leave. Removing evidence can make the cause impossible to establish. If an urgent repair is unavoidable, photograph and measure everything first and keep any removed material.
It also helps to write down, in advance, the questions you want the report to answer. A short list such as "Was this a sudden event or gradual deterioration?", "Is the membrane compliant?" and "Could another source explain the damage?" gives the expert a clear brief. It also stops the report drifting into matters that do not affect who pays, and it makes the final document easier for an insurer or tribunal to act on.
A common point of confusion sits next to this. Some owners searching for a dilapidation report template expect it to do the job of a causation report. It does not. A dilapidation report records the existing condition of a property, usually before or after nearby works such as excavation or demolition, so that any later change can be identified. It documents what is there. A causation report goes further and explains why damage happened. A template can help you structure a condition record, but it cannot analyse the cause of a leak or crack. If your question is "who or what caused this?", you need the second document.
How a causation report is prepared, step by step
A causation report is prepared in five stages, moving from the paperwork to the site and then back to a written opinion. Following them in order is what keeps the conclusion tied to evidence rather than assumption.
- Triage the situation. The expert starts by reviewing symptoms, correspondence, deadlines and documentation. This is where the denial letter, policy wording and your timeline of symptoms do their work. Triage settles the question the report must answer and flags any date that limits how long you have to respond.
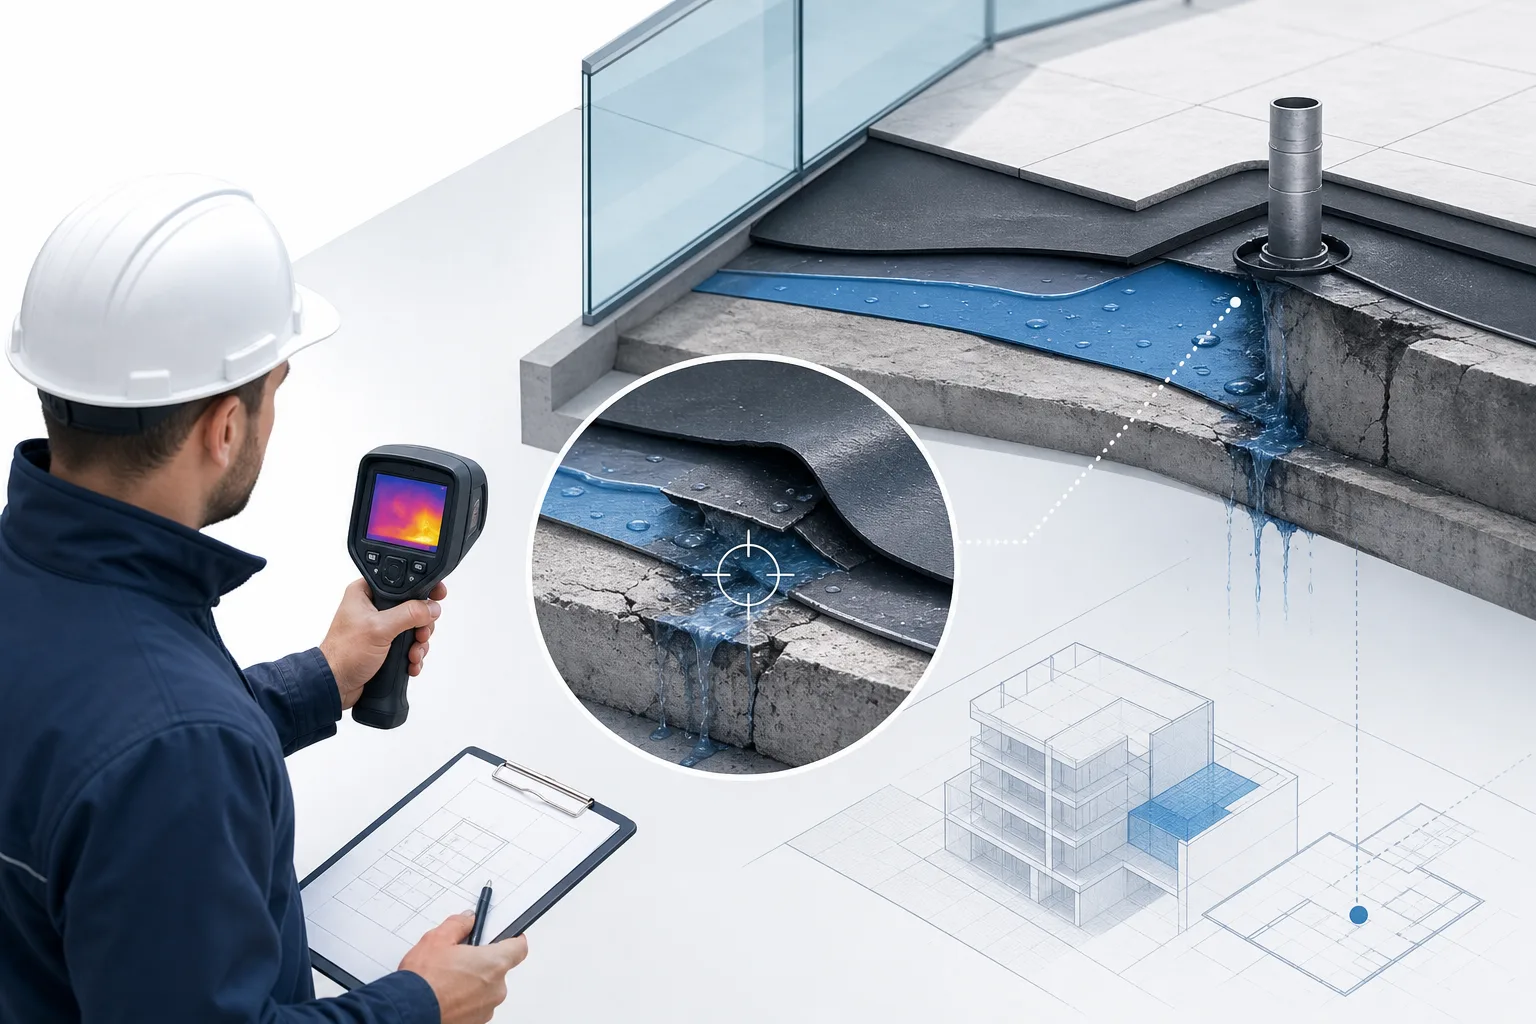
- Capture evidence on site. A systematic forensic inspection follows. The expert records the damage, takes measurements, photographs each area to a consistent protocol and uses instruments such as a moisture meter or thermal imaging camera. Where it is safe and agreed, targeted testing confirms or excludes a suspected source.
- Cross-check against standards. Findings are then compared with the relevant building standards. This is how the report separates a workmanship defect from damage that came from an external event. A non-compliant junction and a storm can both produce the same stain, and the standard is what tells them apart.
- Deliver a structured report. The written report sets out the components described earlier: scope, method, observations, photographs, analysis, standards references, limitations and conclusion. It is written for insurers, assessors and tribunal members who were not on site and must be able to follow the reasoning from the document alone.
- Support the submission. Once the report is lodged, questions often follow. The expert can provide clarifications if an assessor queries a finding, and can support escalation if the claim is challenged again, including through a formal review or tribunal process.
For a concrete case of tracing a cause back through a failed assembly, see Waterproof Membrane Failure: How Inspectors Find the Cause. It shows how an inspector moves from a visible symptom to the entry point of the water, which is the same reasoning a causation report records.
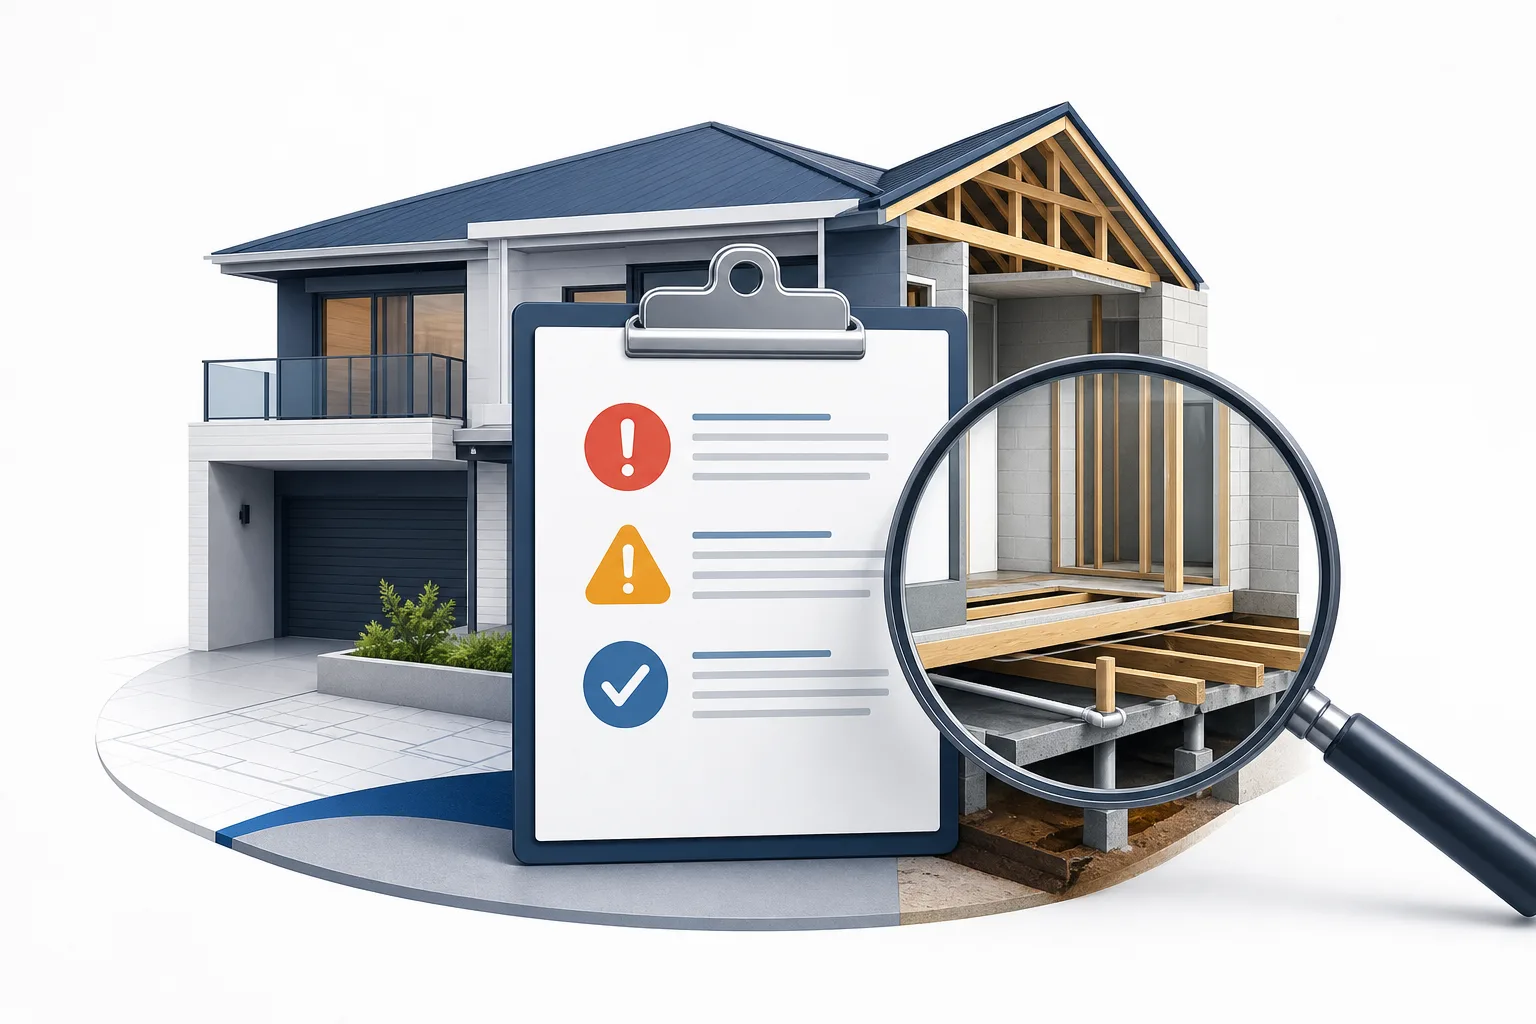
Inspection findings only become usable once they are presented as evidence. The guide to Building Inspection Reports and Expert Evidence explains how an inspection is turned into a document that a tribunal or insurer will accept.
One practical point on timing. Evidence is easier to read when it is fresh, and a deadline for responding to a denial runs whether or not the report is ready. Raise both early with the expert.
It is also worth asking the expert, at the outset, how they will handle any change in the facts. Sometimes opening up a wall reveals a second source of water that nobody had suspected. A good expert will tell you before that happens how they will record it, whether the report will be updated, and what that does to the timetable. Agreeing this early avoids surprises when a deadline is close.
The weight a decision-maker gives the report also depends on how well it is presented. Clear headings, numbered paragraphs, labelled photographs and a plain-language conclusion all help a reviewer who has dozens of files to read. An assessor or tribunal member who can find the key finding in a minute is more likely to engage with the reasoning behind it.
Cost, outcomes and what a causation report cannot promise
The cost of a building causation report depends on the work the question demands, not on a standard rate. The factors below show what moves the cost, so you can scope the job sensibly when you ask for an estimate.
- Site complexity: A single wet area is a smaller job than a whole building with several possible water paths.
- Testing required: Moisture mapping and thermal imaging take less time than opening up walls, ponding tests or specialist testing.
- Number of defects: Each additional defect or damaged area adds inspection time and analysis.
- Access: Roof spaces, sub-floors and concealed cavities take longer to inspect safely.
- Reporting format: A short opinion for an insurer differs in scope from a full report prepared to the Expert Witness Code of Conduct for a tribunal.
- Follow-up work: Answering an assessor's queries or attending a hearing is additional to the report itself.
A medical negligence report is a different exercise. It depends on clinical records and a medical expert rather than a site inspection. It is also a high-volume area overseas. NHS Resolution data indicates that 15,236 new medical negligence claims were submitted during the 2025/2026 period, and in the same year 60% of those claims were resolved with a payment of damages. These are UK health-service figures, not Australian building or insurance data. They are here only to show that medical claims form a separate field with its own experts and cost drivers.
A final cost point is the difference between a staged and a single engagement. Some owners start with a limited inspection to see whether the evidence supports a claim, then commission a fuller report only if it does. That approach can keep the early outlay down, though it may mean the expert visits the site twice. Ask which approach suits your timetable before you agree to either.
On outcomes, you should hear the honest position. There are no reliable success-rate figures for claims after a private causation report is submitted. Insurers and tribunals decide each matter on its facts, and a report cannot bind either. What a report does is improve the quality of the evidence. It replaces a bare assertion about "long-term moisture" with measurements, photographs and a reasoned conclusion, and it gives a reviewer something concrete to weigh. That is a real advantage, but it is not a guarantee.
It also works in both directions. If the evidence shows the damage came from gradual deterioration, an independent report will say so, and that finding spares you the cost of pursuing a claim that will not succeed. An expert who promises a result before inspecting is not offering an independent opinion.
FAQs
What is an insurance causation report?
An insurance causation report is an independent expert document that explains what caused damage to a property and whether that cause falls within an insured event. It records the inspection, measurements, photographs and standards references behind the conclusion. Homeowners use it to respond to a denial that blames maintenance or wear and tear, because it replaces an assumption with documented evidence of how the damage occurred.
Why was my insurance claim denied for maintenance issues?
Most policies cover defined events such as storm or escape of water, and exclude gradual deterioration and lack of maintenance. An assessor may conclude the damage developed over time without testing the point. According to an ICA submission, these exclusions made up 51% of denials in 2023. A causation report examines whether your damage fits the event or the deterioration.
Who prepares a causation report for property damage?
An independent building consultant, licensed builder with forensic experience, or specialist engineer prepares it, depending on what failed. Independence matters more than title. The insurer's own assessor, or the tradesperson who did or repaired the work, has an interest in the answer. In NSW matters the expert should work to the Expert Witness Code of Conduct and give an impartial opinion within their field.
How do I prove medical negligence through a causation report?
Medical negligence needs a medical expert who reviews clinical records and opines on whether a lapse in care caused the harm. That is a different discipline from building inspection. The principle is shared, though: showing a shortfall in standard is only half the case, and a separate opinion must link that shortfall to the injury.
Can an expert use a generic causation report?
No. A template can supply the structure, such as scope, method, observations, analysis and conclusion, but it cannot supply the findings. The measurements, tests, photographs and excluded alternatives are specific to one property and one set of damage. A decision-maker will recognise boilerplate quickly, and a report that does not rest on site-specific evidence carries little weight.
Is a causation report the same as a dilapidation report?
No. A dilapidation report records the existing condition of a property, usually before or after nearby works, so later change can be identified. It documents what is there. A causation report goes further and explains why damage occurred, tracing it to a cause and linking it to standards. If your question is what caused the damage, you need the causation report.
Conclusion
A causation report answers the one question that most denials and disputes turn on: what actually caused this damage? Done well, it replaces an assumption of wear and tear or poor maintenance with measurements, photographs, standards references and a reasoned conclusion from someone who has no stake in the result. It does not guarantee an outcome, and an honest one will tell you if the evidence points the other way.
Start by gathering your denial letter, policy wording, dated photographs and maintenance records, and leave the damaged material in place until it has been inspected. Then ask an independent expert to scope the inspection against the specific question in your denial, and note the date by which you must respond.
Related Posts
Town Planning Expert Witness: When Buyers Need One in NSW
You need a town planning expert witness in NSW when a development application is refused, or approved with conditions you
Read More »
Building Inspector for Apartments: What Buyers Should Check
A building inspector for apartments checks the unit itself: plumbing, electrical, moisture, ceilings, windows, balcony and visible defects. They do
Read More »![Businessman in a suit analyzes a 3D building model on blueprints with a hard hat nearby and a crane in the background, conveying construction planning and law.]](https://awesim.com.au/wp-content/uploads/2026/10/2ba440c4-9d47-4802-adf1-8b6f241eb8ff-768x512.png "2ba440c4-9d47-4802-adf1-8b6f241eb8ff - Awesim Building Consultants")
Construction Claims Experts and Witness Reports
Last updated: 8 November 2026 A construction expert witness provides an independent opinion on technical questions in a building dispute.
Read More »